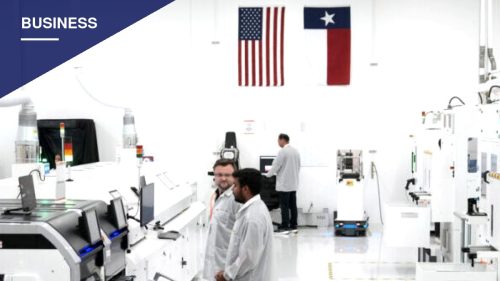
Texas manufacturers reported a sharp acceleration in activity during September, with output, new orders and hiring all climbing well above their historical averages, according to the Federal Reserve Bank of Dallas’s monthly survey.
The survey’s production index, which the Dallas Fed treats as its core gauge of factory conditions in the state, jumped 13.4 points to 29.5 from 16.1 in August. That reading is roughly three times the index’s long-run average of 9.7 and extends a run of expanding output to nine straight months. Just over 41 percent of manufacturers reported higher production in September, while 12 percent reported output declines.
New orders grew even faster than production. The new orders index rose to 30.7 from 22.0 — more than six times its series average of 4.8 — while the growth rate of orders index climbed 11 points to 19.1, far above its historical average of negative 1.0.
Factories appear to be struggling to keep pace with demand. The unfilled orders index swung from negative 1.3 in August to 22.7 in September, well above its long-run average of negative 2.6. Delivery times stretched out, with that index rising to 17.5 from 12.5, and finished goods inventories dropped into negative territory at negative 9.5, down from 2.9 the previous month.
Capacity utilization climbed 11.1 points to 23.9, and shipments rose 10.7 points to 24.8. The Dallas Fed noted that capacity utilization, shipments and new orders all posted readings above their historical averages.
Hiring also picked up. The employment index rose 7.1 points to 15.1 — more than double its series average of 7.1 — marking five consecutive months of job growth. Hours worked stayed roughly flat at 5.6.
What manufacturers are saying
Several respondents to the survey described order books filling up quickly. A machinery manufacturer said it expects a record year for revenue and net income in 2026 as its backlog keeps growing. Another manufacturer reported “a sudden unexpected surge in new orders” following two to three slower months. A third said oil companies are spending at a much higher rate than the company had anticipated.
Costs are rising along with activity. The raw materials prices index rose 8.1 points to 52.2, well above its series average of 28.0, and the finished goods prices index increased to 27.6 from 22.7. The wages and benefits index rose to 27.4 from 21.1. Multiple respondents pointed to diesel fuel costs, and one said it was pricing new jobs on the assumption that diesel would cost $6 a gallon.
Sentiment is mixed despite the surge
Broader sentiment measures did not move in lockstep with the hard numbers. The general business activity index, which reflects how respondents view overall economic conditions rather than conditions at their own firms, slipped to 9.8 from 11.6 but stayed positive for a third straight month. The company outlook index remained positive at 8.7, though it improved more slowly than in August, when it stood at 19.2.
Looking ahead, manufacturers still expect growth to continue. The future production index held near its August level at 40.3, above its series average of 36.0, and the future new orders index came in at 39.5. The future general business activity index fell to 20.8 from 37.2 but remained well above its historical average of 12.5. Expectations for hiring over the next six months cooled more noticeably, with the future employment index dropping to 18.1 from 34.5. Respondents cited energy costs, interest rates and trade policy as ongoing sources of uncertainty.